


BTCC Daily (9.15) | U.S. 10-Year Treasury Yield Tops 5%, Strive Adds 469 BTC Last Week
 BTCCAuthor: jett
Top Highlights
• The Fed begins its two-day policy meeting today. Markets are pricing in about a 90% chance of a 25-basis-point rate hike this week, while 85% of economists in a Reuters poll expect the target range to rise to 3.75%—4.00%.
• The U.S. 10-year Treasury yield rose above 5.02%, the highest since 2007. Middle East supply risks intensified, pushing Brent crude back toward $107 per barrel.
• BTC traded near $77,000. On September 14 ET, U.S. spot Bitcoin ETFs recorded net inflows of about $159.9 million, while spot Ethereum ETFs saw net inflows of about $121.1 million.
Macro & Policy Outlook
Today’s Key Events
• Fed begins its two-day FOMC policy meeting
• U.S. weekly ADP employment
• U.S. September New York Fed Manufacturing Index
• U.S. Senate cloture motion vote on the CLARITY Act
Macro Headlines
1. Fed policy meeting begins, markets price about 90% chance of 25 bps hike
The Fed will hold its two-day policy meeting from September 15 to 16, with markets pricing about a 90% probability of a 25-basis-point hike to 3.75%—4.00% this week. A Reuters poll showed 85% of surveyed economists expect the Fed to take that step. If delivered, it would be the Fed’s first rate hike since mid-2023. Markets will also focus on the dot plot and Chair Kevin Warsh’s comments on the future policy path.
2. U.S. 10-year Treasury yield rises above 5.02%, highest since 2007
The global bond selloff deepened further, with the U.S. 10-year Treasury yield rising above 5.021%, the highest level since 2007. Japan’s 10-year government bond yield also climbed to 3.025%, a 30-year high. Elevated oil prices, inflation pressure, and expectations that major central banks will keep tightening policy jointly pushed long-end yields higher.
3. Saudi East-West oil pipeline remains disrupted, Brent crude returns above $107
Yemen’s Houthi movement launched another attack on Saudi targets after the Saudi East-West oil pipeline was previously hit. The pipeline carries about 4 million barrels per day, equivalent to roughly 4% of global oil supply. Brent crude rose about 1.6% to $107.37 per barrel, while WTI climbed to around $103.24. Planned talks between Gulf states and Iran have also been delayed.
4. China August industrial output rises 5.2%, retail sales increase only 0.4%
China’s value-added industrial output above designated size rose 5.2% year over year in August, above market expectations of 4.8% and July’s 4.5% growth. Retail sales rose only 0.4% year over year, below market expectations of 0.8%. Fixed-asset investment fell 7.2% from January to August, showing that consumption and investment continued to underperform industrial production.
5. Japan 10-year government bond yield hits 30-year high as markets await BOJ hike
Japan’s 10-year government bond yield briefly rose to 3.025%, the highest level in 30 years. The Bank of Japan will announce its policy decision this Friday, with markets broadly expecting a 25-basis-point hike to 1.25% and possibly further tightening signals. The yen’s recent rapid appreciation has also increased attention on this week’s meeting.
Global Asset Performance
• Equities: Japan’s Nikkei 225 closed down 0.01% at 63,484.05. Korea’s KOSPI Index closed down 0.85% at 6,627.26. Among Korean heavyweight tech stocks, Samsung Electronics fell 0.60% and SK Hynix declined 0.53%. U.S. stock futures remained under pressure before the open, with S&P 500 futures down about 0.45% and Nasdaq 100 futures down about 0.44%.
• Crypto: CoinMarketCap data showed the Crypto Fear & Greed Index at 66, in the greed zone. Total crypto market capitalization was about $2.63 trillion, down around 0.9% over the past 24 hours. BTC traded near $77,000, down about 1.24% in 24 hours.
• Energy & Metals: Brent crude rose to around $107.55 per barrel, while WTI crude climbed to about $103.27 per barrel. Spot gold fell about 0.2% to $4,287.69 per ounce, while spot silver declined about 0.4% to $62.98 per ounce.
(Data as of September 15, 15:00 HKT)
Crypto Market Snapshot
1. Futures Capital Flow Analysis
On September 15, according to Coinglass data, ETH, BTC, SOL, SOXL, XAU, and other contracts led net outflows in futures trading over the past 24 hours, potentially signaling trading opportunities.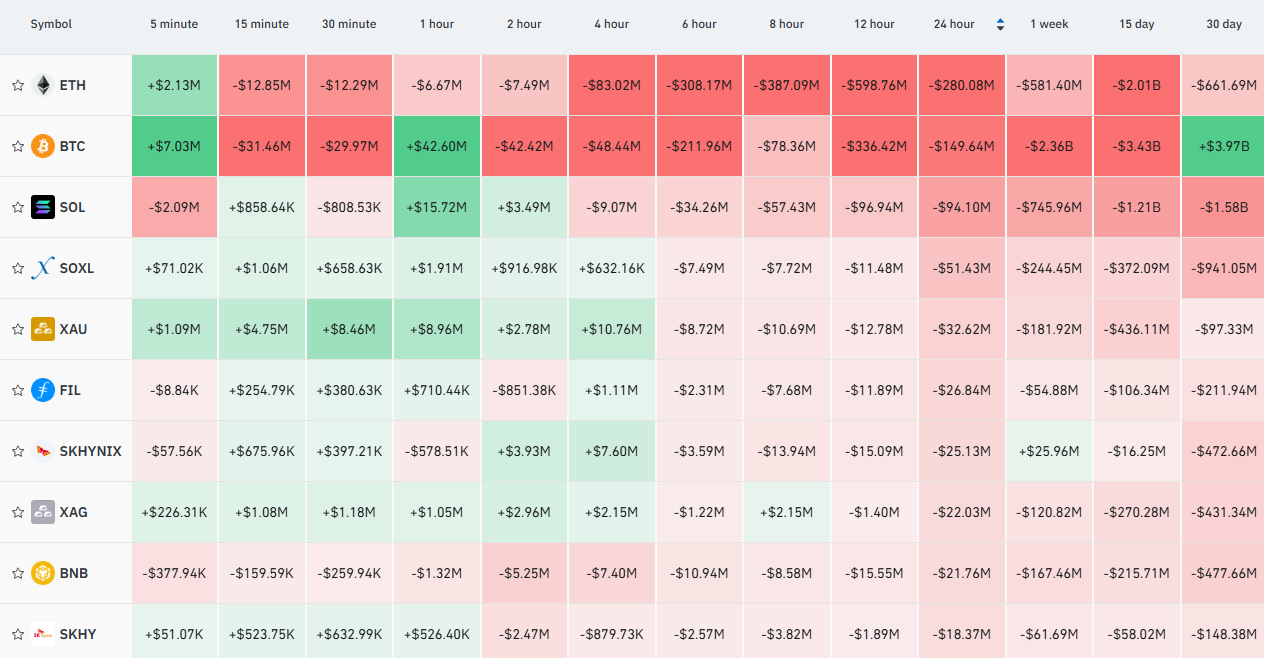
2. Bitcoin Liquidation Map
On September 15, according to Coinglass data, based on the current reference price of $76,907 on the Bitcoin exchange liquidation map, if Bitcoin falls below $75,000, cumulative long liquidation intensity across major CEXs could reach $830 million. Conversely, if Bitcoin breaks above $79,000, cumulative short liquidation intensity across major CEXs could reach $1.01 billion. Traders are advised to manage leverage prudently to avoid large-scale liquidations during market swings.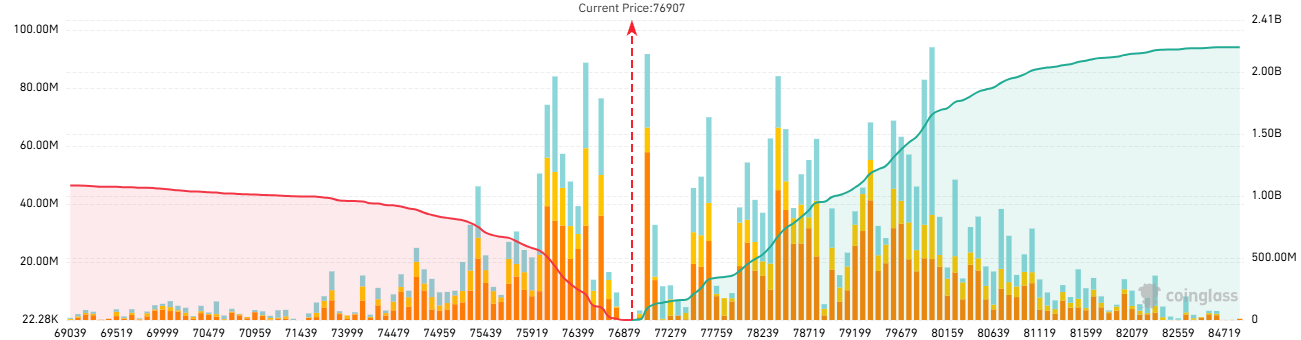
3. Bitcoin Futures Long/Short Ratio
According to Coinglass data, as of 17:00 HKT on September 15, the overall Bitcoin long/short ratio stood at 0.8616, indicating that bears currently hold a relative advantage.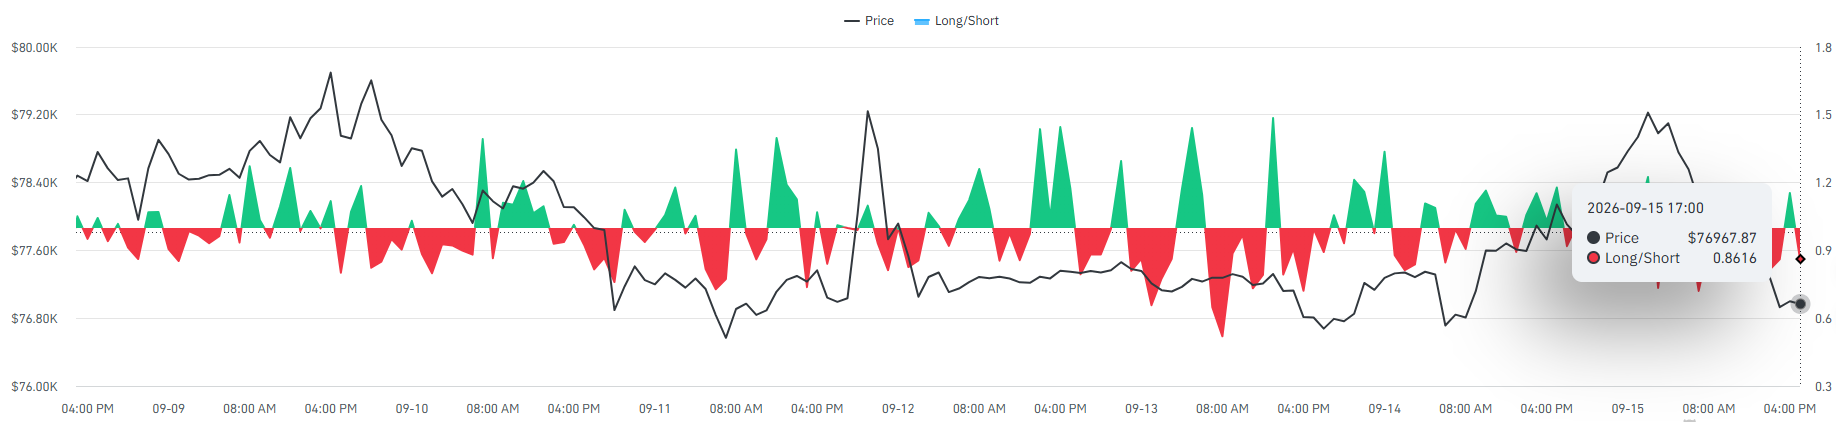
4. TradFi Futures Performance
On September 15, CL rose 0.65%, XAG gained 0.78%, and XAU fell 0.32%. Leveraged tech products came under pressure, with KORU plunging 6.08% and SOXL falling 3.51%, though OI increased by 6.90% and 15.34%, respectively. SPCX rose 0.64%, with trading volume surging 435.40%, showing a clear increase in market activity.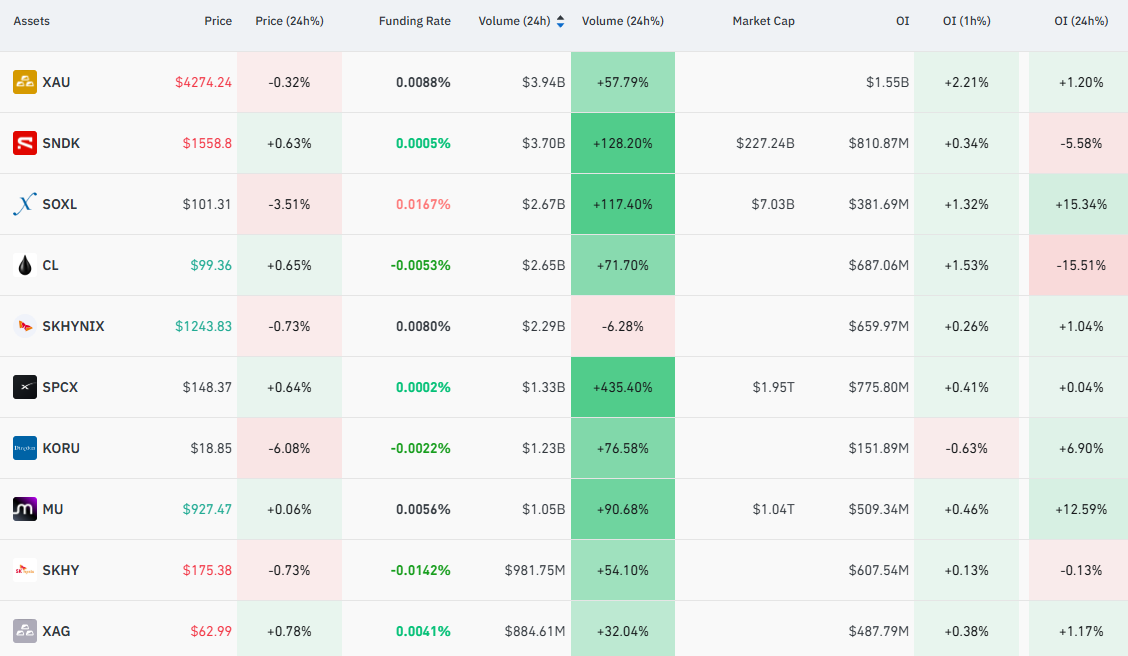
5. On-Chain Monitoring
• A wallet linked to Bitwise’s BHYP transferred 84,320 HYPE to Coinbase, worth about $6.71 million.
• Alameda Research transferred about $9.47 million worth of SOL to Coinbase Prime. It still holds about $270 million worth of SOL on-chain.
• Two wallets dormant for more than one year transferred 14,700 ETH to OKX over the past nine hours, worth about $36.94 million. The two addresses are suspected to belong to the same entity.
Blockchain Headlines
• On September 14 ET, U.S. spot Bitcoin ETFs recorded net inflows of about $159.9 million, including $134.3 million into IBIT and $53.3 million into FBTC, while ARKB saw $42 million in net outflows.
• On September 14 ET, U.S. spot Ethereum ETFs recorded net inflows of about $121.1 million, including $80.5 million into ETHA and $14.4 million into ETHB.
• The U.S. Senate will hold a cloture motion vote on the CLARITY Act at 2:15 p.m. ET on September 15. At least 60 votes are needed to advance the bill to full Senate debate.
• Senate Democrats involved in CLARITY Act negotiations are preparing a counterproposal, while some lawmakers still object to the crypto ethics provisions in the latest Republican version.
• U.S. SEC Chair Paul Atkins said he supports Congress advancing the CLARITY Act, while adding that regardless of the bill’s outcome, the SEC will continue moving forward with its digital-asset regulatory agenda.
• S&P Global led a new funding round for crypto data company Kaiko, raising $110 million, with participation from Nasdaq, BNP Paribas, RBC, and others.
• Strive spent $36.6 million last week to add 469 BTC at an average purchase price of about $77,954, bringing its total holdings to 25,000 BTC.
• Bitmine added 27,180 ETH last week. As of September 13, its total holdings reached about 5.9564 million ETH, of which about 5.0673 million ETH had been staked.
• Strategy did not add more BTC last week and repurchased about $139 million of STRC. As of September 13, the company still held 845,050 BTC and about $6.4 billion in cash assets.
• Ethereum and Base ended their collaboration around account abstraction standards EIP-8130 and EIP-8141. The two sides will continue developing their own account abstraction standards separately.
Institutional Insights · Daily Picks
• Morgan Stanley: The bank shifted to a more hawkish policy forecast, expecting the Fed to raise rates by 25 basis points this week and again by 25 basis points in December. It also expects the ECB to raise rates by another 25 basis points to 2.75% in December. The bank said second-round effects from energy prices, strong demand driven by AI investment, and a higher neutral rate could all keep policy restrictive.
• Bernstein: Gautam Chhugani’s team said the CLARITY Act may advance further than markets previously expected after Republicans made concessions on ethics provisions and community-bank issues. Current crypto market positioning remains cautious, suggesting a positive outcome has not been fully priced in.
• JPMorgan: Mislav Matejka, head of global and European equity strategy, maintained a positive view on U.S. equities. He said that as long as the corporate earnings expansion remains intact, it could be risky to bet solely on high oil prices and rate hikes driving a sustained equity decline. JPMorgan previously raised its year-end S&P 500 target to 8,000.
• MUFG: Analyst Yokoo Akihiko said markets will remain focused in the near term on the inflation impact of higher oil prices and the risk that this pushes rates even higher. With U.S. and Japanese long-term bond yields both rising to multi-year highs, interest-rate volatility remains an important variable for risk assets.
This content is for informational and educational purposes only and does not constitute investment advice related to BTCC. BTCC makes every effort but cannot guarantee the truthfulness, accuracy, or originality of the content above.