


BTCC Daily (9.14) | “Final” CLARITY Act Draft Released, September Fed Hike Odds Rise to 87%
 BTCCAuthor: jett
Top Highlights
• U.S. August CPI rose 0.4% month over month and 3.4% year over year, while core CPI rose 0.3% month over month. Markets raised pricing for a 25-basis-point Fed hike this week to around 87%.
• Asian tech stocks came under clear pressure. Korea’s KOSPI closed down 3.3%, with SK Hynix falling 6.4%, while Japan’s Nikkei 225 declined 0.8%.
• BTC traded near $77,800. On September 11 ET, U.S. spot Bitcoin ETFs recorded net outflows of about $13.29 million, while spot Ethereum ETFs saw net inflows of about $216 million.
Macro & Policy Outlook
Today’s Key Events
• Canada August CPI
• Canada July manufacturing sales
• ECB President Christine Lagarde speaks
• U.S. 3-month and 6-month Treasury bill auctions
Macro Headlines
1. U.S. August core CPI tops expectations, September Fed hike pricing rises to 87%
U.S. August CPI rose 0.4% month over month and 3.4% year over year, both in line with market expectations. Core CPI rose 0.3% month over month, above the expected 0.2%, and 2.4% year over year. With oil prices holding above $100, interest-rate markets raised pricing for a 25-basis-point Fed hike this week to around 87%. Goldman Sachs has shifted to expecting a September hike, while JPMorgan expects 25-basis-point increases in both September and December.
2. U.S. 10-year Treasury yield holds near 4.97%
Long-dated U.S. Treasuries remained under pressure, with the 10-year yield near 4.973%, up about 19 basis points last week. The 2-year yield rose about 26 basis points over the same period. Elevated oil prices and expectations of further tightening by major central banks continued to push global rates higher, leaving the U.S. 10-year yield just below the psychological 5% threshold.
3. Markets price about 76% chance of BOJ 25 bps hike this week
Markets currently price about a 76% probability that the Bank of Japan will raise rates by 25 basis points to 1.25% on Friday. The yen has gained about 4% this month and previously touched a nearly seven-month high of 152.89 per dollar. Beyond the rate decision itself, markets will focus on whether the BOJ signals a faster pace of tightening ahead.
4. Saudi East-West oil pipeline hit, Brent crude rises above $107
Saudi Arabia’s East-West oil pipeline, which is used to bypass the Strait of Hormuz, was hit by a drone attack and temporarily shut down. The pipeline had previously transported about 4 million to 5 million barrels per day. Meanwhile, Houthi threats to shipping in the Red Sea and Bab el-Mandeb rose further. Brent crude climbed about 3% to $107.81 per barrel, while WTI rose to around $102.94.
5. Senate Banking Committee Chair: It is time to pass the CLARITY Act
Senate Banking Committee Chair Tim Scott said on X that it is time to pass the CLARITY Act. He said the bill would protect Americans’ hard-earned money, keep jobs and innovation in the United States, and strengthen national security.
Global Asset Performance
• Equities: Japan’s Nikkei 225 closed down 0.81% at 63,492.99. Korea’s KOSPI Index closed down 3.26% at 6,684.37, with SK Hynix down 6.4% and Samsung Electronics down 4.1%. In U.S. premarket trading, S&P 500 futures fell about 0.6%, Dow futures dropped about 0.3%, and Nasdaq 100 futures declined about 1.1%—1.3%.
• Crypto: CoinMarketCap data showed the Crypto Fear & Greed Index at 68, in the greed zone. Total crypto market capitalization was about $2.66 trillion, up around 0.74% over the past 24 hours. BTC traded near $77,766, up about 0.9% in 24 hours, while ETH was around $2,520. Among large-cap tokens, XMR rose about 4.6% and HYPE gained about 1.6%.
• Energy & Metals: Brent crude rose about 3% to $107.81 per barrel, while WTI crude gained about 2.9% to $102.94 per barrel. Spot gold fell about 0.6% to $4,321 per ounce, while spot silver declined about 1.3% to $63.63 per ounce.
(Data as of September 14, 15:00 HKT)
Crypto Market Snapshot
1. Futures Capital Flow Analysis
On September 14, according to Coinglass data, ETH, BTC, ZEC, SKHYNIX, and other contracts led net inflows in futures trading over the past 24 hours, potentially signaling trading opportunities.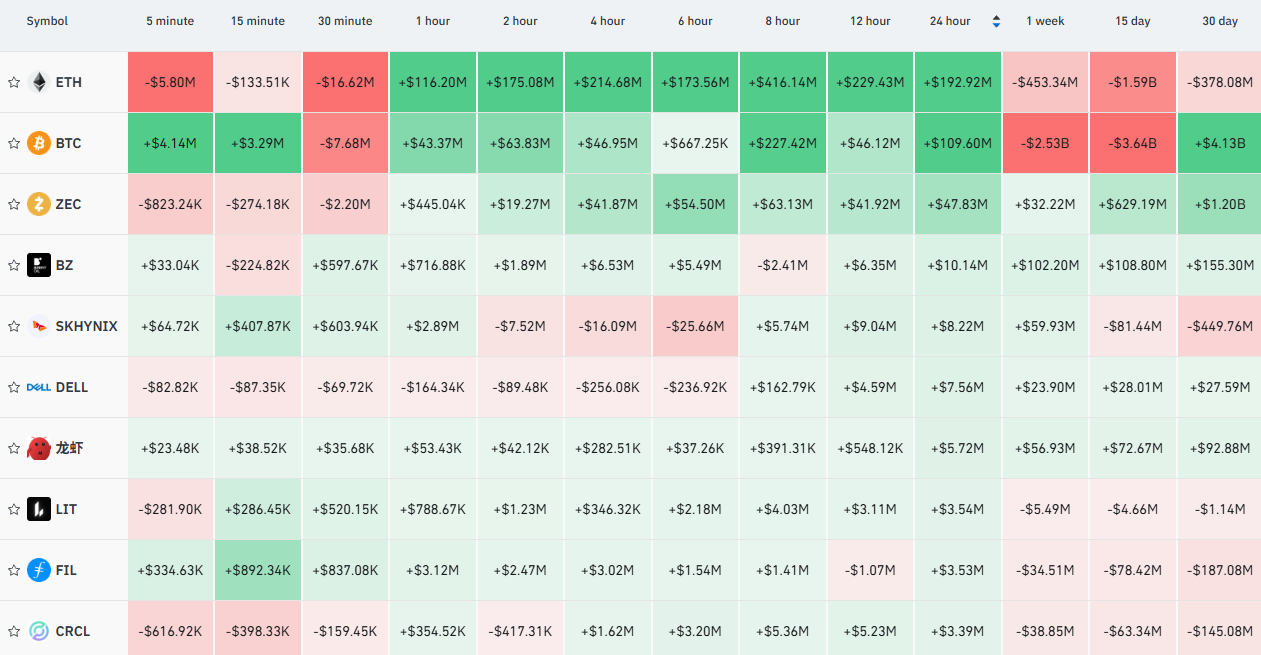
2. Bitcoin Liquidation Map
On September 14, according to Coinglass data, based on the current reference price of $77,607 on the Bitcoin exchange liquidation map, if Bitcoin falls below $76,000, cumulative long liquidation intensity across major CEXs could reach $860 million. Conversely, if Bitcoin breaks above $79,000, cumulative short liquidation intensity across major CEXs could reach $760 million. Traders are advised to manage leverage prudently to avoid large-scale liquidations during market swings.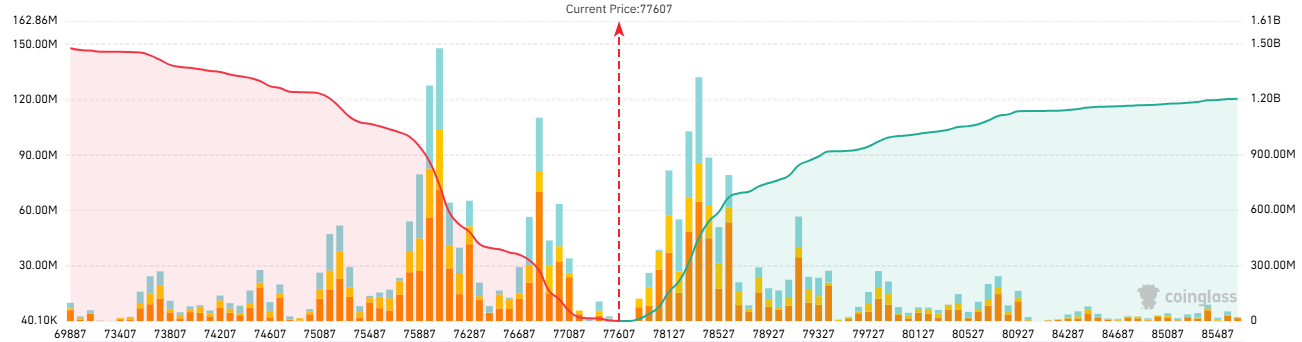
3. Bitcoin Futures Long/Short Ratio
According to Coinglass data, as of 17:00 HKT on September 14, the overall Bitcoin long/short ratio stood at 0.7779, indicating that bears currently hold a relative advantage.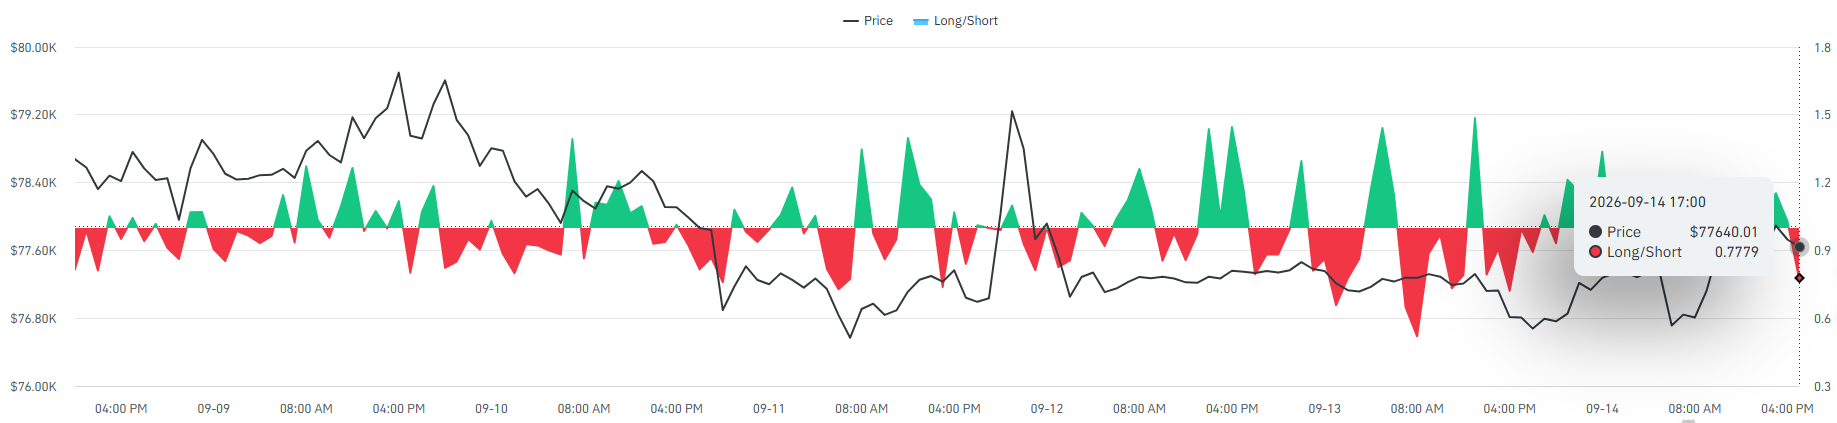
4. TradFi Futures Performance
On September 14, volatility in TradFi contracts expanded sharply. Energy was the strongest segment, with CL and BZ rising 3.26% and 2.65%, respectively. Tech-related contracts came under broad pressure, with SOXL and KORU plunging 11.09% and 11.88%, while SKHY and SNDK also fell notably. Precious metals weakened, with XAU down 1.51% and XAG down 2.92%, though XAU OI rose 12.97%.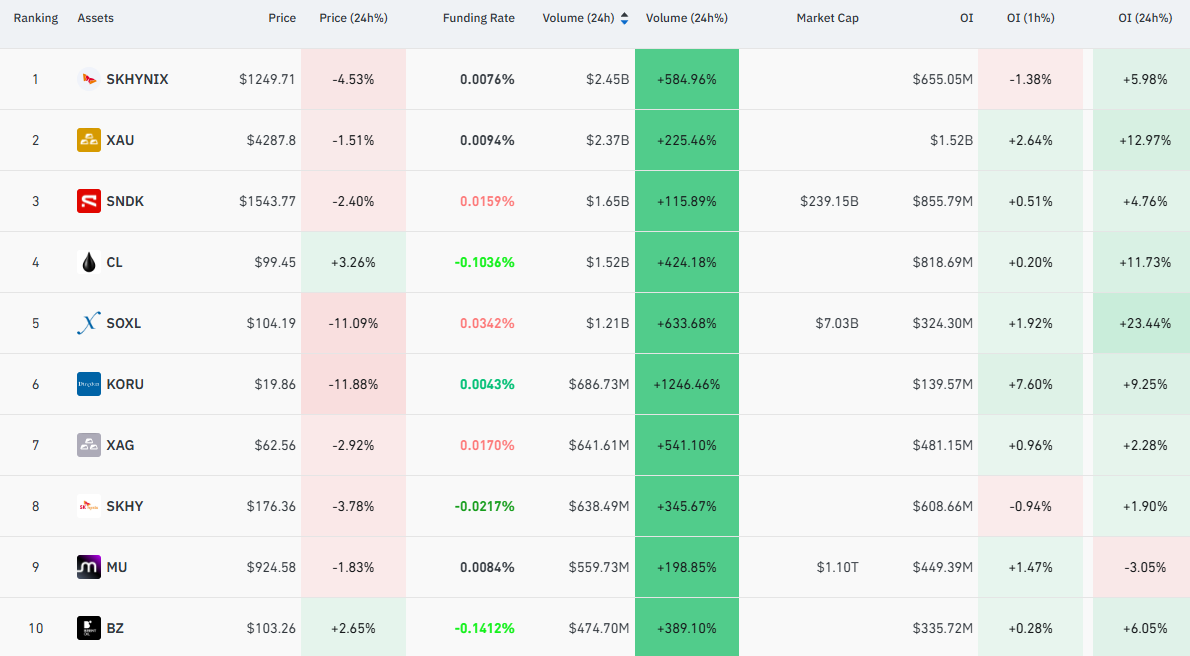
5. On-Chain Monitoring
• According to Lookonchain, whale address 0x3305 bought HYPE for 15 consecutive days, accumulating 358,609 tokens worth about $28.8 million.
• A whale that had been dormant for about eight months used 85.42 million USDC over the past four days to buy a cumulative 1,075.6 BTC through cross-chain transactions, at an average cost of about $79,412, while paying about $170,000 in THORChain transaction fees.
• According to Lookonchain, an address linked to Pump.fun sold another 77,705 SOL, worth about $7.88 million. It has cumulatively sold about 5.1886 million SOL for a total value of about $842 million, at an average sale price of around $162.3.
Blockchain Headlines
• On September 11 ET, U.S. spot Bitcoin ETFs recorded net outflows of about $13.29 million, marking the fourth consecutive trading day of outflows, with IBIT seeing $19.23 million in net outflows. Spot Ethereum ETFs recorded net inflows of about $216 million over the same period, including about $149 million into ETHA.
• Senate Republicans released the “final” draft of the CLARITY Act, adding new crypto-asset ethics restrictions for political figures. The Senate plans to hold a key procedural vote on September 15.
• The UK FCA is studying a dedicated regulatory framework for tokenized gold and is considering exempting some products from existing collective investment scheme and alternative investment fund rules. No final decision has been made.
• FATF President Giles Thomson said criminal groups are increasingly using AI to conduct crypto investment scams, impersonation fraud, and romance scams. FATF will push more countries to establish cross-sector anti-scam centers.
• Circle’s Arc plans to open its public mainnet on September 16, with BlackRock, DTCC, ICE, Mastercard, Visa, Standard Chartered, and others participating as initial validators.
• The U.S. SEC will hold a roundtable on 24-hour stock trading on September 17, covering exchange and broker preparedness, overnight market surveillance, clearing and settlement, liquidity, and investor protection.
• The Eurosystem’s DLT settlement project Pontes is scheduled to launch on September 21. By connecting DLT platforms with TARGET Services, it will enable distributed-ledger transactions to settle in central bank money.
• The UK FCA will open the authorization window for its new crypto-asset regulatory regime on September 30. Applications will be accepted until February 28, 2027, and the new regime is expected to take effect on October 25, 2027.
• Bitdeer disclosed that it mined 293.2 BTC during the week ended September 11 and sold all of it. After excluding customer deposits, the company’s own BTC holdings fell to zero.
• The U.S. CFTC has launched at least three previously undisclosed potential insider-trading investigations involving prediction-market contracts tied to Biden pardons, Iran-related events, and Google’s annual search rankings.
• India’s SEBI launched the Demat 2.0 pilot, with more than $100 million in bonds entering related infrastructure testing in tokenized form in the first phase.
Institutional Insights · Daily Picks
• Goldman Sachs: The bank shifted its September Fed policy forecast from no rate change to a 25-basis-point hike. It still expects two rate cuts in 2027, though the timing may be pushed back from its previous forecast.
• JPMorgan: Chief U.S. economist Michael Feroli expects the Fed to raise rates by 25 basis points in both September and December and raised his long-run policy-rate forecast to 3.25%. He said failing to act in the current inflation environment could weaken the Fed’s policy credibility.
• Goldman Sachs: Chief U.S. equity strategist Ben Snider said corporate earnings can still support U.S. equities. Across seven historical rate-hike cycles, the S&P 500 fell by an average of about 2% in the first three months after hikes began, but posted an average 12-month return of about 9% after the first hike.
• UBS: Strategist Joni Teves said further Fed tightening could pressure gold in the short term, but central-bank buying, asset-allocation demand, and seasonal demand from India and China should continue to provide support. She expects gold prices may strengthen again before year-end.
This content is for informational and educational purposes only and does not constitute investment advice related to BTCC. BTCC makes every effort but cannot guarantee the truthfulness, accuracy, or originality of the content above.