


Binance Research: AI Trade Shifts From Semiconductors to Software and Capital Markets
 chaincatcher
Author: Lim Kim Thye
Compiled by: Wu Blockchain
Key Takeaways
· As unit capacity costs continue to decline, growth in token usage benefits hyperscale cloud service providers, whose infrastructure business margins range from 33% to 38%.
· The ratio of capital expenditure to operating cash flow has risen from 41% in 2023 to approximately 105% in 2026. The combined free cash flow of related companies has turned negative, and the funding gap is beginning to be filled by debt financing.
· The market's pricing logic has changed: capital expenditure that cannot be converted into actual growth will be punished, while investments that can drive AI revenue growth will receive positive feedback.
· Market concentration is declining. Binance investors are also reducing their concentrated allocation to the semiconductor sector, shifting funds toward software and capital markets.
Token Maximization Trend Ends in Q2, Two Curves Begin to Diverge
The second quarter ended the assumption that "increased token consumption directly translates into model-layer revenue." Companies realized that token consumption and productivity are not linearly related, so they no longer blindly pursue maximizing token usage. At the same time, AI agents are rapidly proliferating, and the market is paying more attention to the efficiency of tokens required to complete a single task. The development focus of frontier models has also shifted from inference benchmarks to agent programming, memory architecture, and lower-cost lightweight inference.
As of early September 2026, weekly token usage routed through OpenRouter reached 137 trillion, approximately 20 times the level at the beginning of the year. Open-weight models account for more than half of the inference tokens in production environments on that platform, up from one-third in the previous study, and the top five models by token usage all use open weights. These models have capabilities approximately 90% of closed-source models, but the cost per call is only about one-sixth of the latter. Stripe has reduced its GPU cluster to one-third of its original size while maintaining 50 million daily calls, cutting inference costs by 73%.
As a result, the benefits of AI growth have begun to diverge. Enterprises select models based on specific tasks, and an AI agent typically requires thousands of tokens to complete a task, making low-cost open-weight models key to achieving the economic viability of long-running agents. As unit capacity costs decline, growth in token usage benefits hyperscale cloud infrastructure providers with margins of 33% to 38%, but companies that directly sell model capabilities find it harder to convert this into revenue. 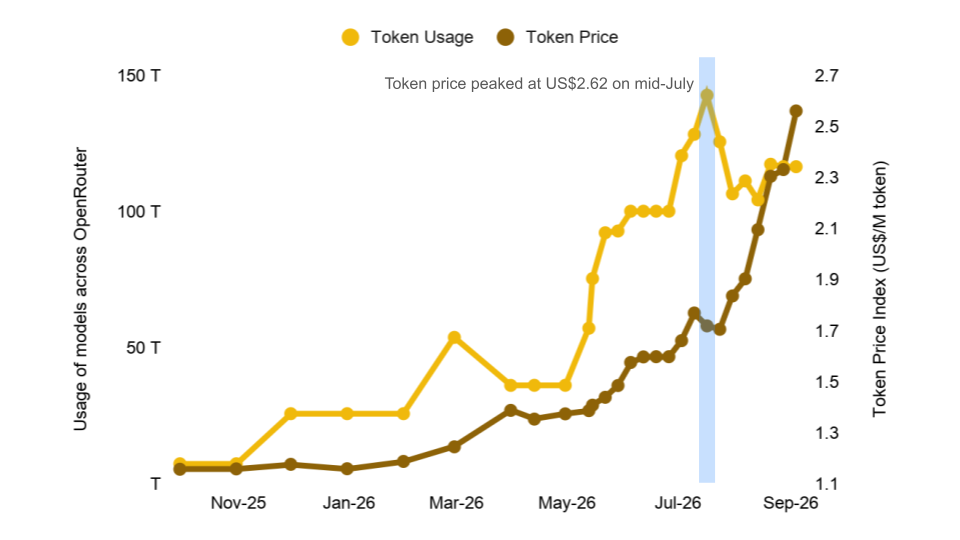
Figure 1: Token usage approaches 150 trillion, token price index peaks at $2.62 in July
Capital Expenditure Exceeds Operating Cash Flow
The 2026 capital expenditure guidance provided by the five major U.S. cloud computing companies totals between $725 billion and $800 billion, depending on whether finance leases and prepayments are included.
More noteworthy than the absolute amount is the ratio of capital expenditure to operating cash flow. The capital expenditure of these five companies has risen from 41% of operating cash flow in 2023 to approximately 105% in 2026. This means that the funds they use to expand infrastructure capacity have exceeded the cash generated by their core businesses.
This change is quickly reflected in free cash flow. Alphabet's free cash flow this quarter was negative $5.9 billion, the first negative figure since its listing. Meta's free cash flow fell from $8.5 billion in the same period last year to $784 million. Over the past 12 months, Amazon's free cash flow was negative $7.6 billion, and Oracle consumed $23.7 billion in cash in fiscal year 2026. The combined free cash flow of the five companies turned from positive $246 billion in 2024 to approximately negative $37 billion in 2026, the first negative turn in this investment cycle.
As internal cash can no longer support investment needs, external financing has become the primary source of funds. The share of debt financing in hyperscale cloud service providers' capital expenditure rose from 9% in fiscal year 2024 to 32% in the 12 months ending mid-2026, with total debt of the five companies at approximately $700 billion.
An observation by the Bank for International Settlements (BIS) is particularly noteworthy: the loan spread for AI private credit is approximately 6.2 percentage points, close to the financing spread for non-AI borrowers. In other words, the risks already reflected in the stock market have not yet been fully reflected in credit market pricing. 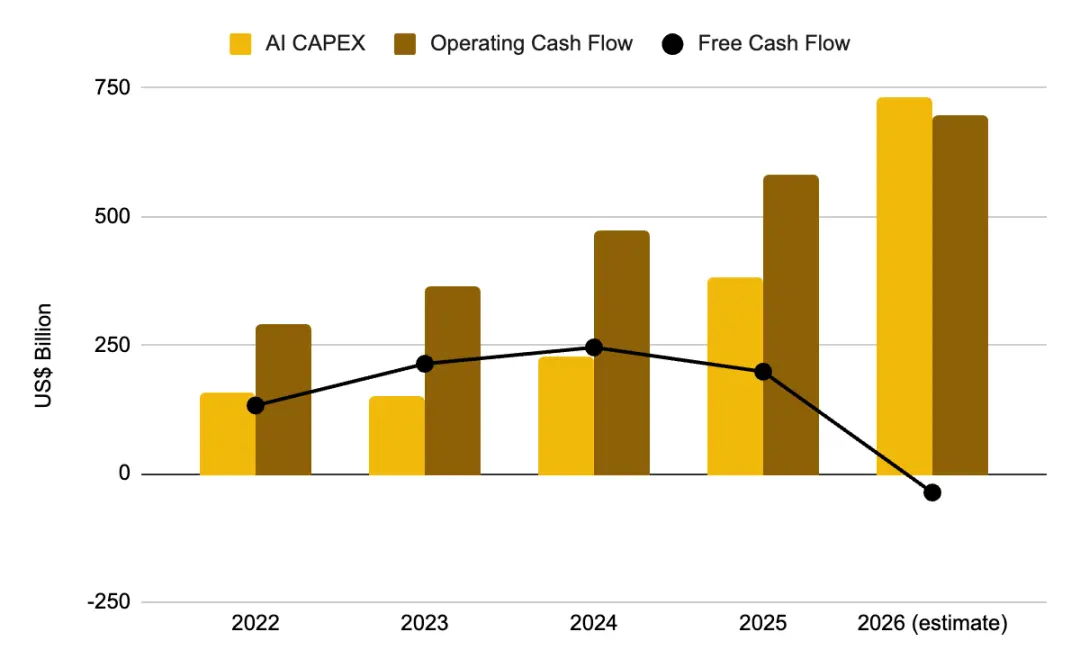
Figure 2: Capital expenditure exceeds operating cash flow in 2026, free cash flow turns negative
Demand Signals Are Huge, but Monetization Cycle Is Long
Three companies show the same trend.
· Google Cloud revenue grew 82% to $24.8 billion, operating margin rose from 20.7% to 35.6%, and unfulfilled contract amount reached $514 billion. Google Cloud currently processes 22 billion tokens per minute, up from 16 billion in the previous quarter.
· Microsoft's remaining performance obligations (RPO) reached $678 billion, up 84% year-over-year. Azure revenue grew 43%, and Microsoft 365 Copilot has over 30 million paid seats.
· Oracle's remaining performance obligations reached $638 billion, up 363% year-over-year. However, the company's disclosed data shows that only about 12% will convert to revenue within the next 12 months, and about 20% will not be realized until five years later.
On the model company side, Anthropic's annualized revenue is approximately $47 billion, and OpenAI's is approximately $25 billion. Both companies are currently loss-making and preparing for IPOs. Goldman Sachs estimates that token consumption will grow to 24 times current levels by 2030, but only 12% of knowledge workers will use agent AI by then.
The scale of these numbers is indeed massive, but very little can be converted into actual revenue in the short term, and this time lag is key to the subsequent analysis in this report. Unfulfilled orders do exist, and capital expenditure has already occurred, but hyperscale cloud service providers and frontier model companies must convert contractual demand into recognized revenue quickly enough to justify these investments. At the same time, the underlying assets supporting these businesses typically need to be depreciated over four to six years. 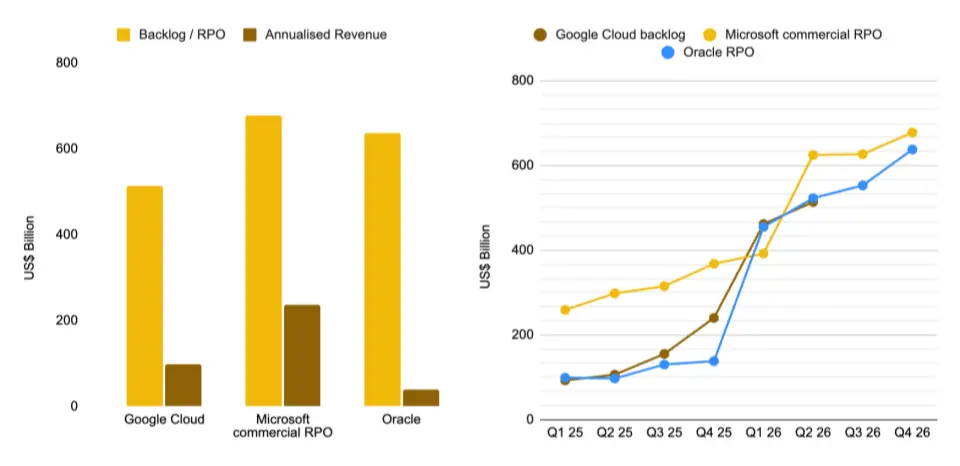
Figure 3: Unfulfilled orders far exceed current revenue, Google Cloud at $514 billion, Oracle at $638 billion
Market's Pricing Logic Has Reversed
Investors have begun to factor these elements into pricing, and the latest earnings season clearly reflects this change.
Overall data is insufficient to fully capture this shift; individual stock performance is more representative. Among index constituents, companies that beat earnings per share expectations rose an average of 0.6%, below the five-year average of 1.0%; companies that disappointed fell an average of 2.5%, also less than the five-year average of 3.0%. The market's overall reaction to both positive and negative news has weakened, but significant divergence has emerged within the AI sector.
Calculated from the first full trading day after earnings announcements, the divergence is very clear. Alphabet's revenue grew 24% and cloud business grew 82%, but the stock fell 7.13%, solely because the company raised its capital expenditure guidance. Meta fell 7.95% due to lower-than-expected earnings per share, another increase in capital expenditure, and free cash flow dropping to $784 million.
The other side is equally striking. Microsoft's Azure revenue grew 43%, remaining performance obligations grew 84%, and it slightly lowered capital expenditure for calendar year 2026, driving the stock up 15.51%, the largest single-day gain since 2008.
Amazon raised capital expenditure to $220 billion, but as AWS growth accelerated back to 37%, the stock still rose 15.32%, with market capitalization surpassing $3 trillion. Nvidia rose 8.74%. Palantir, which can expand infrastructure with almost no capital investment, rose 29.45%.
The market's criteria are now very clear: unless investment is proven to be converting into growth, capital expenditure is a burden. This is why, although both Alphabet and Amazon raised capital expenditure, Alphabet was punished by the market while Amazon received positive feedback. 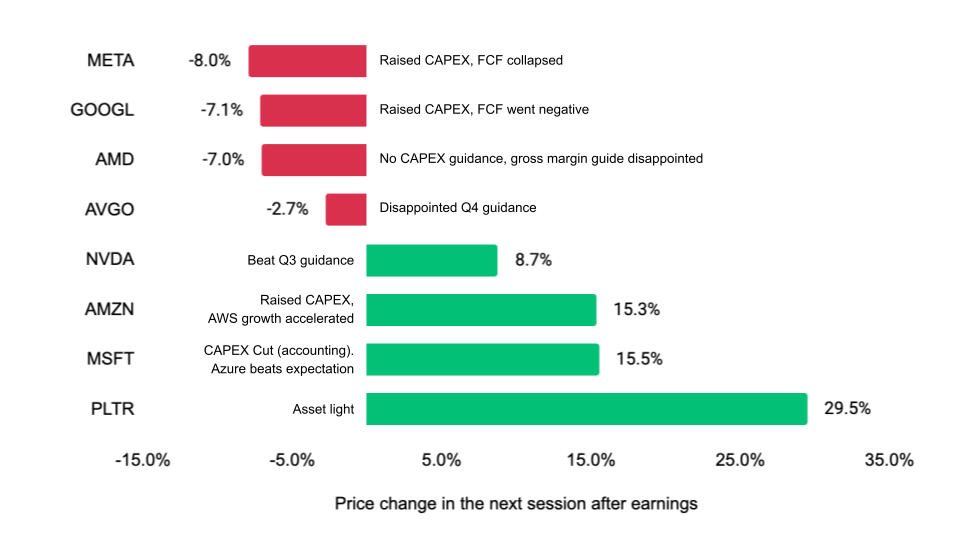
Figure 4: Same increase in capital expenditure, completely opposite results, Alphabet down 7.1%, Amazon up 15.3%
2026 Market Main Theme Is Diffusion, Not Further Concentration
Market concentration has peaked and begun to decline. The weight of the "Magnificent Seven" in the S&P 500 index fell from approximately 35.3% in October 2025 to 33.2% in September 2026. As of August, the S&P 500 index is up 12.28% year-to-date, the Nasdaq Composite is up 13.46%, and the Russell 2000 small-cap index is up 19.12%.
Among these, the performance of small-cap stocks is particularly noteworthy. This indicates that the AI trade is spreading to indirectly benefiting industries such as industrials and utilities, rather than further concentrating in mega-cap software companies. The equal-weight index outperformed the market-cap-weighted index by approximately 3.6 percentage points, showing that after the most accessible gains have been realized, funds are flowing to more volatile secondary beneficiaries.
However, current valuations limit the room for this rotation to continue. The S&P 500's forward price-to-earnings ratio is approximately 19.6 times, slightly below the five-year average of 19.9 times, but above the ten-year average of 19.0 times. The interest rate environment also provides no support, with the effective federal funds rate at 3.63% and the 10-year U.S. Treasury yield at 4.77%.
Therefore, the current conclusion is the opposite of last year: the 2026 market rally is spreading to more industries and companies of different market capitalizations, and passive portfolios' overweight positions in AI leaders are shrinking rather than continuing to increase. 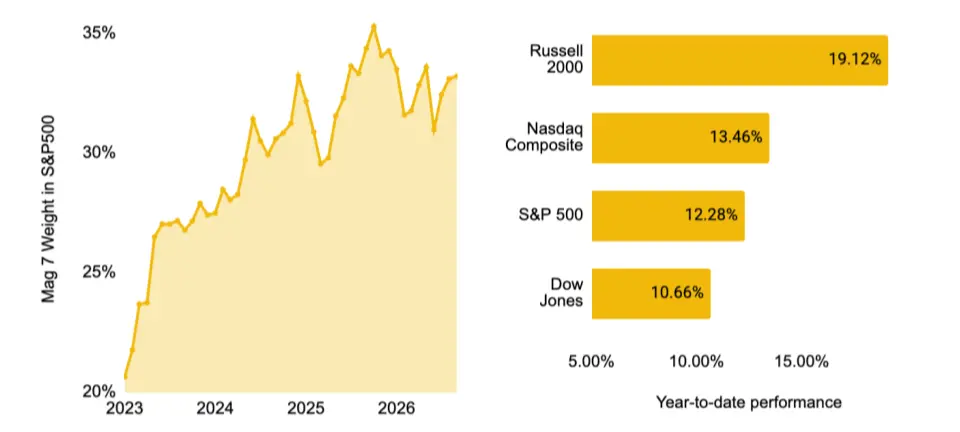
Figure 5: "Magnificent Seven" weight retreats from peak, Russell 2000 leads with 19.12% year-to-date gain
Binance Investors Are Also Diversifying, but Starting From a More Concentrated Base
Comparing data from end-June 2026 and September 4 shows that the adjustment direction of the S&P 500 index is broadly consistent with Binance users' holdings. The semiconductor sector's weight in the S&P 500 fell from 18.8% to 14.8%, and the technology hardware sector fell from 6.8% to 6.2%; Binance investors adjusted more sharply, with their technology hardware holdings falling from 15.92% to 7.94%.
During the same period, the weights of almost all other sectors in the S&P 500 increased slightly, indicating that funds did not shift to another single theme but dispersed from previously highly concentrated areas to multiple sectors. Binance investors continued to reduce holdings in aerospace and defense, interactive media and services, and industrials, while increasing holdings in capital markets, software, and general retail sectors.
There are three main differences between Binance investors and the benchmark index: semiconductor allocation is as high as 42.08%, significantly higher than the S&P 500; capital markets sector allocation reflects their crypto-related preferences; and holding concentration is also higher, with the top ten sectors accounting for approximately 92% of their equity allocation, compared to approximately 53% combined weight of the top ten sectors in the S&P 500. 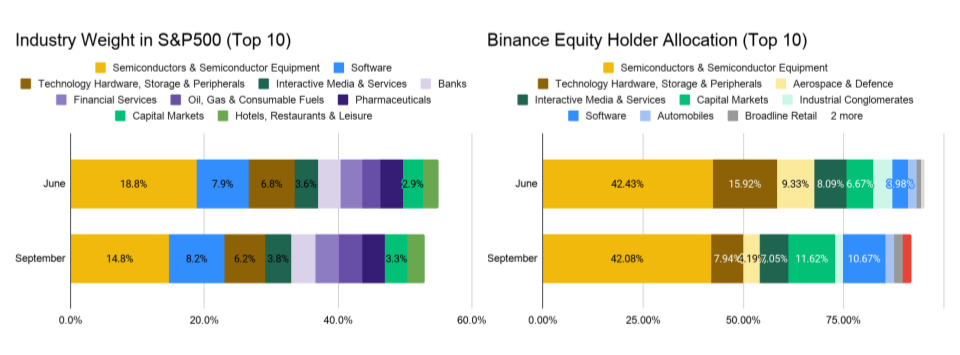
Figure 6: From June to September, semiconductor weight declines in both S&P 500 and Binance user holdings
Monthly Fund Flows Reflect Sector Rotation in Real Time
Monthly net fund flows further confirm the market diffusion trend and clearly show the process of investors adjusting positions month by month.
In July, investors continued to allocate around the AI theme and remained optimistic ahead of earnings season. Most investors bought during the market pullback at the end of July, with the semiconductor sector absorbing most of the net inflows, and the capital markets sector also receiving significant funds.
In August, investors turned cautious. They began to take profits on capital markets stocks while continuing to add to semiconductors, but the pace of inflows slowed significantly. At the same time, a large amount of funds shifted to the software sector, and overall net inflows for the month fell to about half of July's level.
Since September, the semiconductor sector saw its first monthly net outflow, as rising long-term interest rates pressured risk assets. However, it should be noted that current data only covers the first week of September, and the upcoming Federal Reserve interest rate decision could quickly reverse this trend.
Looking at the three months of data together, portfolios were still highly concentrated in AI hardware at the beginning of the quarter, then gradually spread to software, capital markets, and other secondary beneficiary industries. This is consistent with the sector rotation observed in the benchmark index, but comes from a different investor group and adjusts more rapidly. 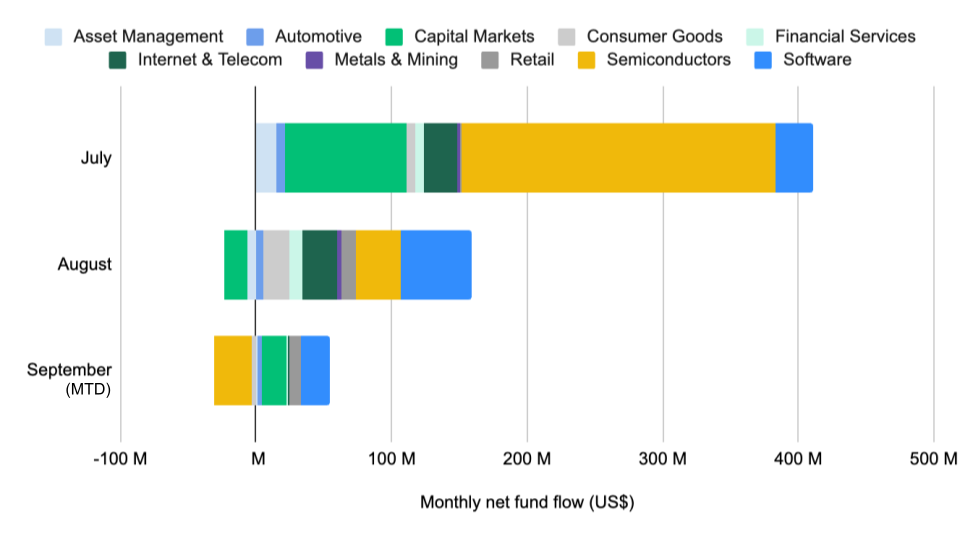
Figure 7: From July to September, funds flow out of semiconductors and into software
Trading Volume Highly Consistent With Investor Holdings
Trading activity closely matches the asset allocation structure of investors. The top ten sectors by trading volume are essentially the same as the sectors primarily held by Binance investors. This suggests that investors are more likely to be continuously building and adjusting existing positions rather than engaging in short-term rotation between unrelated themes.
In September, the semiconductor sector led with a 33.84% share of trading volume, with capital markets and software sectors accounting for 16.71% and 13.67% respectively. These three together account for approximately 64% of the trading volume of the top ten sectors. The technology hardware sector followed closely at 10.42%, consistent with the aforementioned trend of investors reducing holdings in that sector.
The concentration of holdings and trading in the same sectors is an important signal when interpreting fund flows. When trading volume is concentrated in sectors where investors are increasing holdings, the related fund movements are more likely to represent clear allocation intentions rather than being driven purely by short-term turnover.
Pre-IPO Perpetual Contracts Can Directly Price Counterparty Risk
Binance's Pre-IPO perpetual contracts allow investors to establish positions on private company valuations not yet available on other major platforms. After Anthropic reported quarterly revenue growth of over 100% and achieved a small operating profit, its contract price rose approximately 35% in August; after OpenAI released its latest frontier model Astra, its contract price rose approximately 23% in early September, reflecting the market's real-time judgment on model releases.
These two model companies contribute a significant portion of AI revenue to hyperscale cloud service providers. Wells Fargo estimates that over 70% of Microsoft's AI revenue comes from these two companies; Barclays estimates that these two companies contribute approximately 73% of Amazon's AI revenue; UBS expects that these two companies' share of Google Cloud's total revenue will rise from 28% in 2026 to over 48% in 2027. The $300 billion contract OpenAI signed with Oracle also accounts for approximately half of Oracle's $638 billion in unfulfilled orders.
Therefore, actual customer concentration is higher than what overall capital expenditure data suggests, with related revenue highly concentrated in these two unlisted counterparties. If either of them experiences a significant growth slowdown, the impact will transmit from hyperscale cloud service providers' AI revenue to Oracle's unfulfilled orders, and further affect securitized products supported by suppliers that provide financing for related infrastructure. Currently, Pre-IPO perpetual contracts are one of the few tools that can directly hedge such specific risk exposures. 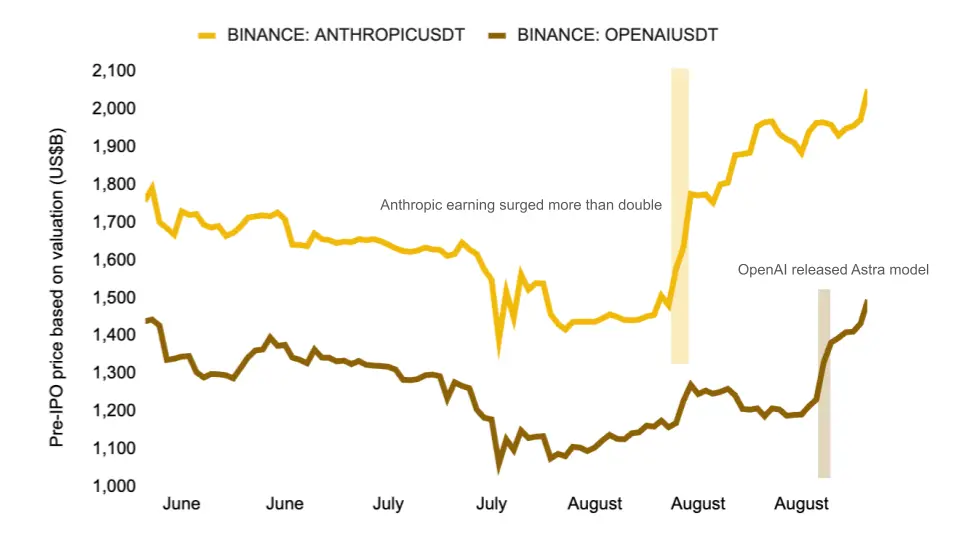
Figure 8: Pre-IPO contract prices repriced after Anthropic's earnings and OpenAI's Astra launch
This content is for informational and educational purposes only and does not constitute investment advice related to BTCC. BTCC makes every effort but cannot guarantee the truthfulness, accuracy, or originality of the content above.