


Is the Failure of the Clarity Act a Bad Outcome?
 chaincatcher
Author: Zhou, ChainCatcher
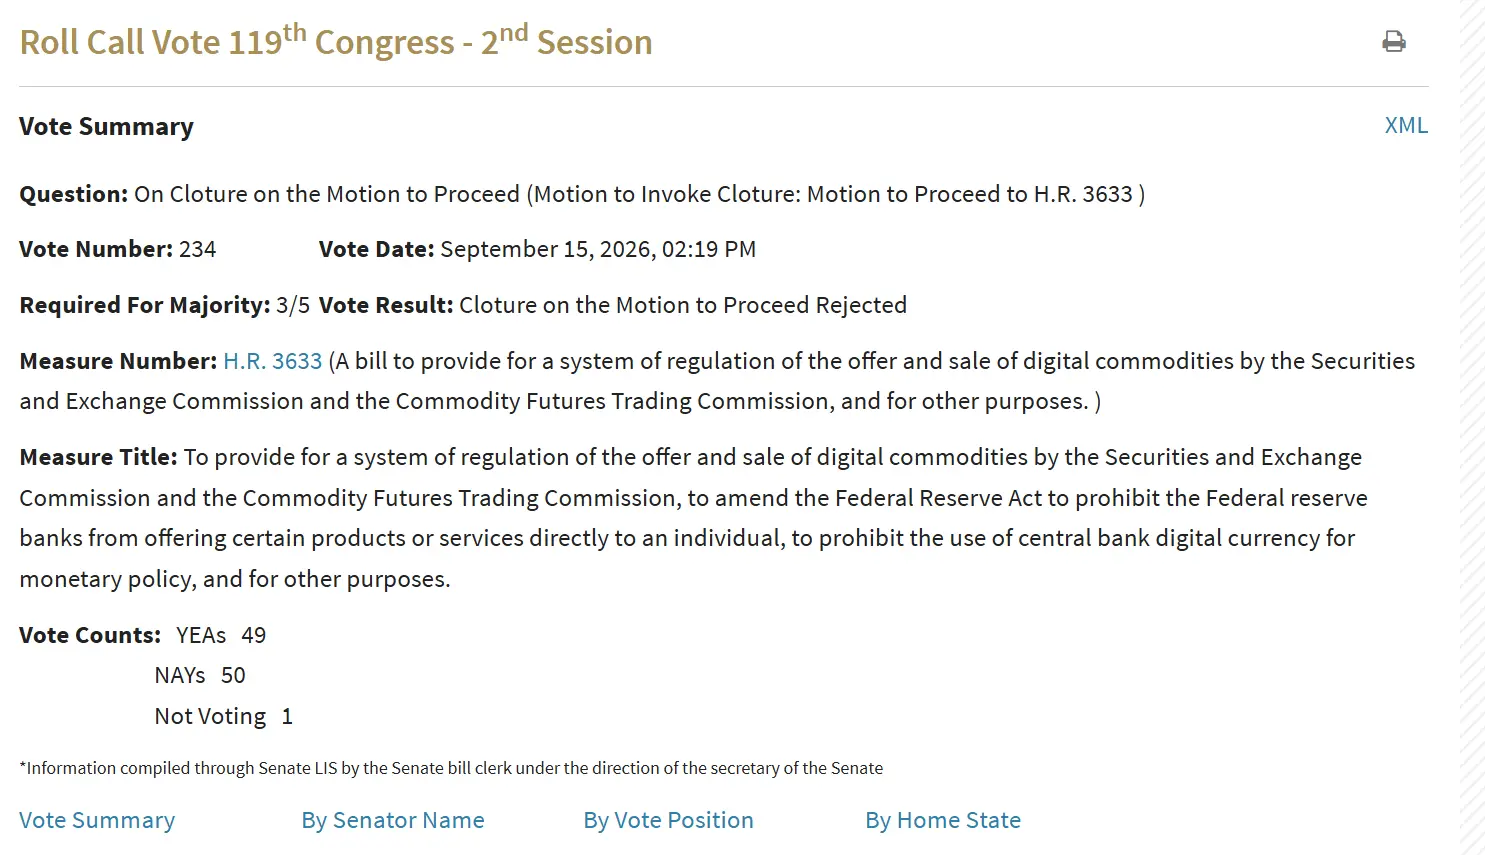
In the early hours of September 16 Beijing time, the U.S. Senate held a cloture vote on the Digital Asset Market Clarity Act, which failed with 49 votes in favor and 50 against, falling short of the 60-vote threshold required for passage. Republicans currently hold 53 seats, with at least three members not voting in favor.
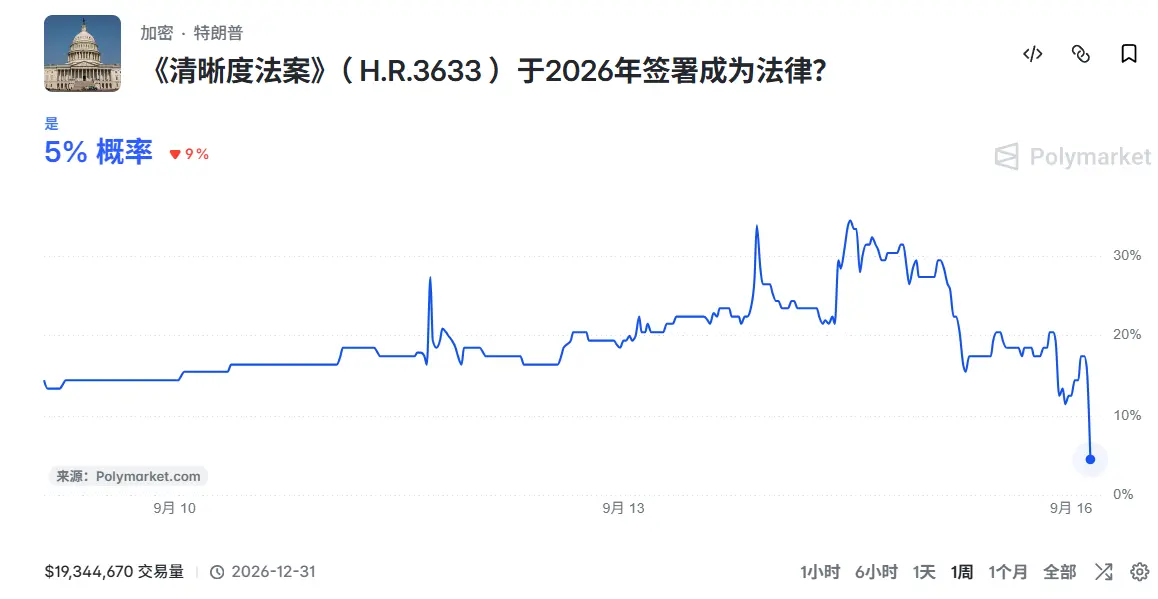
After more than a year of back-and-forth and two delayed votes, the bill still failed to clear this hurdle. Following the news, Bitcoin briefly dropped to around $75,000, and crypto-related stocks such as Coinbase, Circle, Robinhood, and Strategy fell collectively. On Polymarket, the probability of the bill becoming law by the end of 2026 dropped from over 30% earlier in the week to about 5%.
The immediate cause of the failure was that Democrats did not accept the text released by Republicans on September 14. Republicans called that version the final proposal before the vote, but Democratic negotiators did not accept it and submitted a counterproposal hours before the vote. Mark Warner later said that while disputes over enforcement and national security were close to resolution, the conflict-of-interest issue regarding public officials profiting from the crypto industry remained unresolved, leading him to vote against it. Democrats involved in negotiations, such as Ruben Gallego, Angela Alsobrooks, Kirsten Gillibrand, Catherine Cortez Masto, and Cory Booker, ultimately all sided with the opposition.
The counterproposal remained stuck on ethics provisions. Core disputes included expanding the scope of restrictions, requiring forced divestment of equity in certain crypto companies, tightening enforcement and disclosure requirements for sponsors, and adding protections related to DeFi. The revised text still did not restore the criminal safe harbor for developers, miners, and validators from the BRCA. Katie Warbinton, spokesperson for Senator Cynthia Lummis's office, responded that if Democrats truly wanted to reach an agreement, they should engage in genuine negotiations rather than resubmitting their original demands and calling it progress. Neither side made further concessions before the vote.
However, this setback only means the bill temporarily cannot enter formal consideration and amendment procedures; it does not equate to a final rejection. There is currently no timeline indicating whether another attempt to gather 60 votes can be made within the year.
What concessions did Republicans make?
On the eve of the vote, the September 14 text was drafted by Republicans as the final proposal before the vote. Compared with the July merged draft, changes focused on ethics provisions, stablecoin yields, DeFi and developer protections, and Agriculture Committee provisions.
Specifically, on ethics provisions, Trump accepted about 80% of the proposal by Thom Tillis and Ruben Gallego, requiring federal elected officials, judges, and their spouses who hold significant economic interests in token issuers to divest their holdings or place them in blind trusts. State attorneys general were granted partial enforcement authority for the first time, but limited to prosecuting trading platforms that list non-compliant assets, not touching the president himself. Previously this authority was granted only to the federal attorney general. The provision is set to sunset in 2029, and existing holdings do not need to be liquidated.
On stablecoin yield provisions, payment stablecoins in principle still cannot pay passive interest solely because users hold them. The new text includes a circuit breaker mechanism of up to 18 months; if there are signs of large-scale deposit outflows from community banks to stablecoins, federal regulators can intervene, with the Treasury Secretary Scott Bessent deciding whether to trigger it. This is a direct result of months of lobbying by the banking industry, but eight groups including the American Bankers Association are not satisfied, arguing that the circuit breaker only activates after deposits have already fled.
On DeFi and developer protection provisions, decentralization is divided into two scenarios. Those that truly do not handle user assets, such as validators, node operators, and those who publish wallet software, receive clearer safe harbor exemptions. Trading protocols that are nominally decentralized but still retain control must register with the CFTC and comply with the Bank Secrecy Act. The BRCA, or Blockchain Regulatory Clarity Act, has also been narrowed, removing previous references extending to criminal cases and retaining only Bank Secrecy Act and civil protections.
What does it mean for exchanges, stablecoins, and protocols?
The Clarity Act has stirred the crypto market because it touches on three unresolved questions: whether digital assets are securities or commodities, whether the SEC or CFTC should take the lead, and whether stablecoins fall between payment instruments and deposit-like products, as well as the boundaries of rewards. Protocols must achieve a higher degree of decentralization to avoid being treated as regulated intermediaries.
For exchanges, the real change lies in the compliance cost of listing assets. The ethics provisions delegate prosecution authority to state attorneys general, meaning exchanges must consider not only federal compliance lines but also face accountability risks from various states when reviewing tokens. Letitia James led 18 state attorneys general in sending a joint letter before the vote, stating that the text would weaken the first line of defense against fraud at the state level.
Miles Jennings, head of policy at a16z crypto, believes that arrangements such as customer asset segregation, qualified custodians, and conflict-of-interest restrictions are exactly the mechanisms that were lacking when FTX collapsed. The bill essentially transplants rules that have long existed in traditional financial markets into the crypto industry. Nate Geraci, president of ETF Store, reminded that these changes are more about enhancing certainty and accelerating innovation, and the bill itself is not the key variable determining the direction of cryptocurrencies.
For stablecoin issuers and related banks, the 18-month circuit breaker mechanism does not truly resolve banks' concerns, which is one of the specific reasons for the loss of Republican votes. Eight groups including the American Bankers Association sent a letter to Senate leaders of both parties, arguing that the circuit breaker would only activate after large-scale deposit outflows have already occurred and cannot provide real protection.
Republican Senator John Cornyn publicly stated before the vote that the new text may still not address the core concerns of community banks, which is one reason he was seen as a potential no vote. The White House Council of Economic Advisers had tried to use an interactive tool to refute the claim that stablecoin growth would squeeze community bank deposits, but failed to change the stance of banking groups and lawmakers like Cornyn.
For protocols, the real watershed is whether the team is willing to give up control, and the way this line is drawn leaves all parties dissatisfied. Coin Center, a developer rights organization, expressed disappointment over the narrowing of BRCA protections, believing that removing references extending to criminal cases weakens previously achieved developer protections.
Mike Novogratz, founder of Galaxy Digital, said that the inadequacy of developer protection provisions is one reason at least four Republican senators opposed it, showing that this dissatisfaction exists not only in the developer community but also permeates the Republican base.
Failure to pass does not mean regulation is zero
So, is this a bad outcome for the market?
Previously, Mike Novogratz had said that if the bill cannot move forward, the U.S. may not have crypto legislation for a long time, or even ever, leading more industry segments to move overseas. White House crypto adviser Patrick Witt also mentioned that once the procedural vote fails, no one can predict when the next window will open.
However, there are also voices arguing that the regulatory process will not be interrupted by a single vote. SEC Chairman Paul Atkins said that regardless of whether the bill passes, the SEC will continue to advance the Project Crypto agenda, including formulating rules for crypto asset issuance, incorporating blockchain ownership ledgers into transfer agent rules, and clarifying custody requirements for investment advisers and regulated funds.
Zach Pandl, head of research at Grayscale, pointed out that regulatory frameworks in areas such as stablecoins, token issuance, tokenized securities, and perpetual futures are gradually becoming clearer, and the GENIUS Act has already established a federal framework for payment stablecoins. Bernstein warned that if legislation is blocked, combined with signals of monetary policy tightening, crypto assets and crypto stocks could see a significant pullback.
This proposal, which Republicans called the "last, best, and final" offer, did not secure 60 votes, but it left behind the bottom line of Republican willingness to concede, which may become the starting point for the next round of negotiations.
This content is for informational and educational purposes only and does not constitute investment advice related to BTCC. BTCC makes every effort but cannot guarantee the truthfulness, accuracy, or originality of the content above.